The semiconductor industry is built upon one of the most complex and interconnected supply chains in the global manufacturing economy. From raw materials and specialty chemicals to semiconductor equipment, wafer fabrication, packaging, and final electronic products, each stage influences the economics of the entire value chain. Among these relationships, the transmission of price changes from semiconductor materials to foundry manufacturing costs has become an increasingly important topic as the industry experiences supply shortages, capacity expansions, and technology transitions.
Unlike traditional manufacturing industries where raw material costs often represent a large share of production expenses, semiconductor manufacturing operates under a different economic structure. Materials account for only a portion of total wafer production costs, but their strategic importance is significantly higher because material availability, purity, and performance directly affect production yield and manufacturing stability.
Empirical observations across multiple semiconductor cycles indicate that price changes in upstream materials are transmitted to foundry manufacturers through several channels, including direct cost increases, supply constraints, contract adjustments, and capacity allocation decisions. However, the degree and speed of transmission vary significantly depending on the material category, technology node, market conditions, and bargaining power between suppliers and foundries.
Understanding this price transmission mechanism provides valuable insight into semiconductor cost structures, supplier competitiveness, and future industry trends.
The Semiconductor Supply Chain and Price Transmission Mechanism
The semiconductor supply chain consists of multiple interconnected layers. Upstream suppliers provide raw materials and process chemicals, equipment companies supply manufacturing tools, foundries transform wafers into chips, and downstream companies integrate semiconductors into electronic products.
Within this structure, semiconductor materials occupy a unique position. Materials such as silicon wafers, photoresists, specialty gases, polishing materials, and electronic chemicals are consumed continuously during production. When material prices increase, foundries must evaluate whether these costs can be absorbed internally or transferred to customers through higher wafer pricing.
The transmission process is not immediate. A material price increase typically moves through several stages:
First, material suppliers adjust pricing due to higher production costs, limited capacity, or increased demand. Second, foundries experience higher manufacturing expenses. Third, foundries evaluate utilization rates, customer contracts, and market competitiveness before adjusting wafer pricing. Finally, downstream semiconductor customers may reflect these increases in chip prices.
This multi-stage process explains why material price movements often appear before changes in semiconductor pricing.
The Role of Materials in Foundry Cost Structures
Foundry manufacturing costs consist of several major components, including depreciation of manufacturing equipment, labor expenses, facility operations, energy consumption, materials, and process-related costs.
Although equipment depreciation represents a significant portion of advanced semiconductor manufacturing costs, materials remain critical because they directly influence production continuity and yield performance.
For advanced semiconductor processes, material requirements become increasingly demanding. Smaller process nodes require higher-purity chemicals, more advanced photoresists, improved deposition materials, and stricter contamination control. As a result, the cost and complexity of materials increase alongside technological advancement.
However, the impact of material price changes on total wafer costs depends on the specific product category. For mature semiconductor processes, material costs may represent a larger proportion of manufacturing expenses because equipment costs have already been amortized. For advanced nodes, material costs may represent a smaller percentage but remain strategically important due to their impact on yield.
Silicon Wafer Price Transmission to Foundries
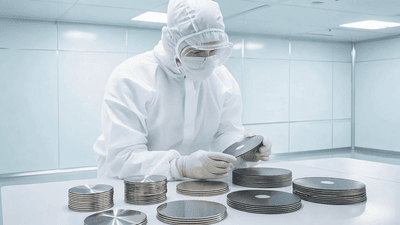
Silicon wafers represent one of the most fundamental materials in semiconductor manufacturing. Every semiconductor device begins with a high-quality silicon substrate, making wafer pricing closely connected with foundry operations.
Historically, silicon wafer prices have experienced cyclical fluctuations based on semiconductor demand, capacity utilization, and supplier investment cycles. During periods of strong semiconductor demand, wafer suppliers often face capacity constraints, allowing them to increase prices.
Foundries usually experience silicon wafer cost increases before customers see direct pricing changes. The ability of foundries to pass these costs downstream depends on market conditions.
When semiconductor demand is strong and foundry capacity is limited, wafer price increases can often be transferred to customers. Advanced semiconductor customers with urgent capacity requirements may accept higher wafer prices to secure supply.
During weak market conditions, however, foundries may absorb more of the cost increase because competition for customer orders becomes stronger.
Photoresist and Chemical Cost Transmission
Photoresists and semiconductor chemicals provide another important example of price transmission. These materials are essential for lithography, cleaning, etching, and other wafer fabrication processes.
Advanced photoresists, particularly those used in extreme ultraviolet lithography, have relatively high technical barriers and limited supplier availability. When supply becomes constrained, material suppliers may have stronger pricing power.
However, the transmission of chemical price increases to foundries is often influenced by qualification complexity. Semiconductor manufacturers cannot easily replace suppliers because new materials require extensive testing and process validation.
This creates a situation where even small material price increases may have significant strategic importance. Foundries may accept higher material costs to maintain production stability rather than risk production disruption.
Specialty Gas and Energy-Related Cost Effects
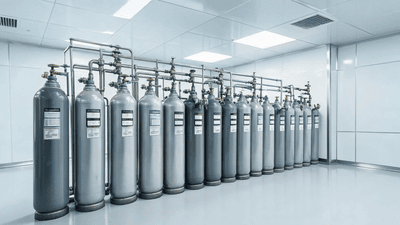
Specialty gases are another important category where price changes can affect semiconductor manufacturing economics. Semiconductor fabrication requires highly purified gases for deposition, etching, and cleaning processes.
Supply disruptions in specialty gases can create significant production risks because alternative sources may not be immediately available.
When gas prices increase due to raw material shortages, energy costs, or supply chain disruptions, foundries evaluate the impact based on both cost and availability. In some cases, maintaining stable supply becomes more important than minimizing short-term costs.
This demonstrates that semiconductor price transmission is not driven only by cost increases. Supply security and operational risk also influence pricing decisions.
Empirical Evidence From Semiconductor Cycles
Historical semiconductor cycles provide several examples of material-to-foundry price transmission.
During periods of semiconductor shortages, upstream materials often experience price increases before foundry pricing adjusts. Limited availability of wafers, chemicals, and specialty components creates pressure throughout the manufacturing chain.
As foundry utilization rates rise, manufacturers gain stronger pricing power. They can increase wafer prices because customers prioritize supply availability over cost reduction.
Conversely, during semiconductor downturns, material prices often decline before foundry prices adjust downward. This occurs because material suppliers respond quickly to reduced production demand, while foundry contracts and customer pricing structures change more slowly.
This asymmetric behavior shows that price transmission is not identical during expansion and contraction cycles.
Factors Influencing Transmission Speed and Magnitude
Several factors determine how strongly material price changes affect foundry pricing.
The first factor is supply concentration. Materials controlled by a small number of suppliers generally have stronger pricing power. Limited competition allows suppliers to maintain higher prices during periods of strong demand.
The second factor is customer qualification difficulty. Materials that require long approval processes create stronger supplier relationships and reduce substitution options.
The third factor is semiconductor market conditions. When foundry capacity utilization is high, manufacturers are more capable of passing costs to customers. When utilization is low, cost transmission becomes more difficult.
The fourth factor is technology level. Advanced semiconductor processes require more specialized materials, increasing sensitivity to supply conditions.
The Impact of Advanced Nodes on Material Pricing
The transition toward advanced semiconductor nodes has increased the importance of material innovation. Technologies below traditional manufacturing levels require new materials with improved performance and lower defect rates.
Advanced logic chips, artificial intelligence processors, and high-performance computing devices depend on sophisticated material systems. These include advanced photoresists, high-purity chemicals, specialized deposition materials, and new substrate technologies.
Although the direct cost contribution of these materials may remain limited compared with equipment investment, their strategic value is much greater because they determine whether advanced manufacturing processes can achieve acceptable yields.
This creates a new form of price transmission where material suppliers compete not only on cost but also on technological capability.
The Influence of Foundry Bargaining Power
Foundries occupy a central position in the semiconductor supply chain and their bargaining power strongly affects price transmission.
Leading foundries with advanced technology capabilities and high customer demand generally have stronger negotiating positions. They can work with multiple suppliers and optimize manufacturing processes to control costs.
However, even major foundries face limitations when dealing with highly specialized materials. If only a few suppliers can provide qualified materials, foundries may have limited ability to resist price increases.
This balance between supplier power and foundry power determines how much of a material price increase reaches the final semiconductor customer.
Future Trends in Semiconductor Material Pricing
Looking ahead, semiconductor material pricing is expected to become increasingly influenced by technology transitions, supply chain localization, and demand growth from emerging applications.
Artificial intelligence, electric vehicles, renewable energy, and advanced computing will continue increasing demand for semiconductor manufacturing capacity. This will create additional pressure on critical materials.
At the same time, semiconductor companies and governments are investing in supply chain diversification. New material production capacity may reduce dependence on limited suppliers and improve long-term price stability.
However, advanced semiconductor manufacturing will continue requiring highly specialized materials. Technology leadership will remain a major factor determining pricing power.
Conclusion
The transmission of semiconductor material prices to foundry manufacturing costs is a complex process shaped by supply conditions, technology requirements, market cycles, and bargaining relationships.
Empirical analysis shows that material prices often move ahead of foundry pricing because materials are directly connected to production activity. However, the speed and degree of transmission vary depending on material type and market conditions.
As semiconductor manufacturing becomes more advanced and supply chains become more strategic, material suppliers will play an increasingly important role in determining industry economics.
Understanding the relationship between material pricing and foundry costs provides valuable insight into semiconductor market cycles, manufacturing strategies, and future competitive dynamics.